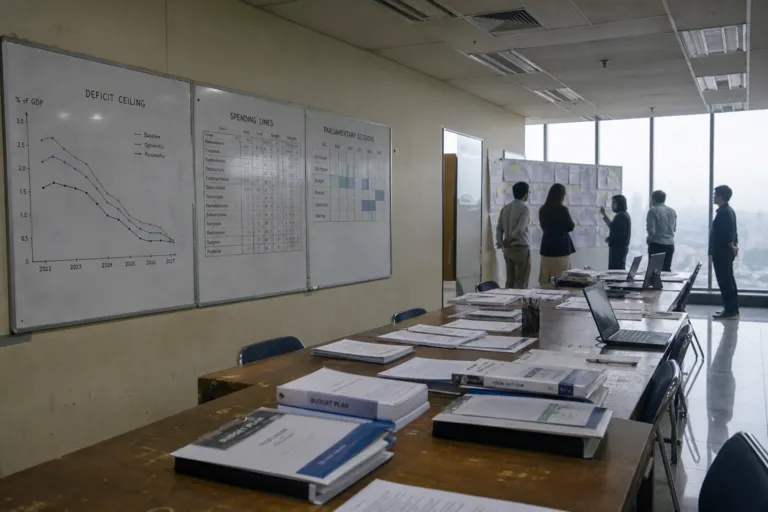
Indonesia’s statutory budget deficit ceiling of 3% of GDP has become a focal point for investors again, not only because the deficit is nearing that line, but because parliament is now openly debating whether the rule should change. Reuters reported that a potential revision to the long-standing ceiling has undermined confidence, at a time when policymakers are pursuing costly welfare agendas and aiming for faster growth. In this context, the indonesia fiscal deficit limit is being treated by markets as more than a number; it is a test of policy credibility and discipline that has been respected since the law was enacted in 2003.
On the near-term numbers, Finance Minister Purbaya Yudhi Sadewa projected the 2026 state budget deficit would widen to Rp734.3 trillion (about US$45.1 billion), equivalent to 2.85% of GDP, above the original budget target of Rp689.1 trillion (about US$42.3 billion), or 2.68% of GDP. Indonesia Business Post linked the wider gap to stronger-than-budgeted spending, projected at Rp3,942.4 trillion (about US$242.3 billion), or 102.6% of the original allocation. At the same time, the Finance Ministry projected state revenue would also exceed its target, reaching Rp3,208.1 trillion (about US$197.2 billion), with non-tax revenue expected to outperform assumptions.
Why the 3% Rule Is Being Challenged—and Why Markets Care
IndexBox, citing Reuters, said lawmakers are reviewing amendments to the state finance law that sets both a 3% maximum annual deficit and a 60% public debt ceiling—guardrails that were put in place after the Asian Financial Crisis of the late 1990s and have been respected since 2003. Some lawmakers argue the cap constrains welfare ambitions and growth expansion, while others warn that if Indonesia fails to discipline itself, “the market will ultimately discipline it.” The Diplomat reported that debates are likely to be watched closely by institutional investors, while also noting a brokerage view that raising the ceiling could provide greater flexibility in financing government programs.
For investors, risk is not limited to whether the deficit prints at 2.68% or 2.85%. Indonesia Business Post quoted Piter Abdullah of the Prasasti Center for Policy Studies saying a deficit approaching 3% does not automatically signal rising macroeconomic risks; instead, investors focus on fiscal governance and spending quality. He cited scrutiny around governance-related issues, including Danantara Indonesia and the Koperasi Desa Merah Putih (KDMP) program. Reuters also framed market unease around policymaking credibility and predictability, noting Moody’s and Fitch cut their credit rating outlooks to negative from stable, and that MSCI flagged transparency issues and warned of a possible downgrade of Indonesia to frontier market status, triggering a market rout of more than $120 billion.
Policy shocks can also turn a ceiling debate into a pricing problem across assets. Indonesia Investments warned that “breaching or consistently flirting with the 3 percent cap” risks negative outlooks or downgrades from global credit rating agencies. It also described how a larger-than-planned deficit can require more borrowing via government bonds (SBN), potentially pushing yields higher and raising financing costs more broadly. On revenues, it said tax revenue realization by year-end may only reach IDR 2,310.8 trillion (approx. USD $128.7 billion), below the targeted IDR 2,357.7 trillion (approx. USD $131.3 billion). Separately, Reuters reported the finance ministry assessed that if global oil prices reached around $90 to $92 per barrel, the deficit could widen to around 3.6% of GDP without budget adjustments—underscoring why investors track both rule changes and scenario risks.
What is Indonesia’s current legal budget deficit ceiling?
How close is the 2026 deficit projection to the ceiling?
Why are lawmakers debating changes to the Indonesia fiscal deficit limit?
What risks do investors watch beyond the headline deficit number?
What scenario could push the deficit above 3% of GDP without adjustments?